- admin
- June 26th, 2026
September 18th, 2026
- admin
- September 18th, 2026
Everything Looks Bad. Your Plan Doesn't Change.
Oil touched $109 last week and remains above $103. Interest rates may be heading higher. Indian equities have gone sideways for nearly two years. Here is what it means, and what to do about it.
For nearly two years, Indian equity investors have had to exercise something that rarely comes naturally in markets: patience without much visible reward. The Nifty has remained largely range-bound, and just when the domestic environment appeared to be turning, the RBI had cut rates by 125 basis points over 18 months, from 6.5% to 5.25%, providing genuine relief, the global backdrop has shifted again.
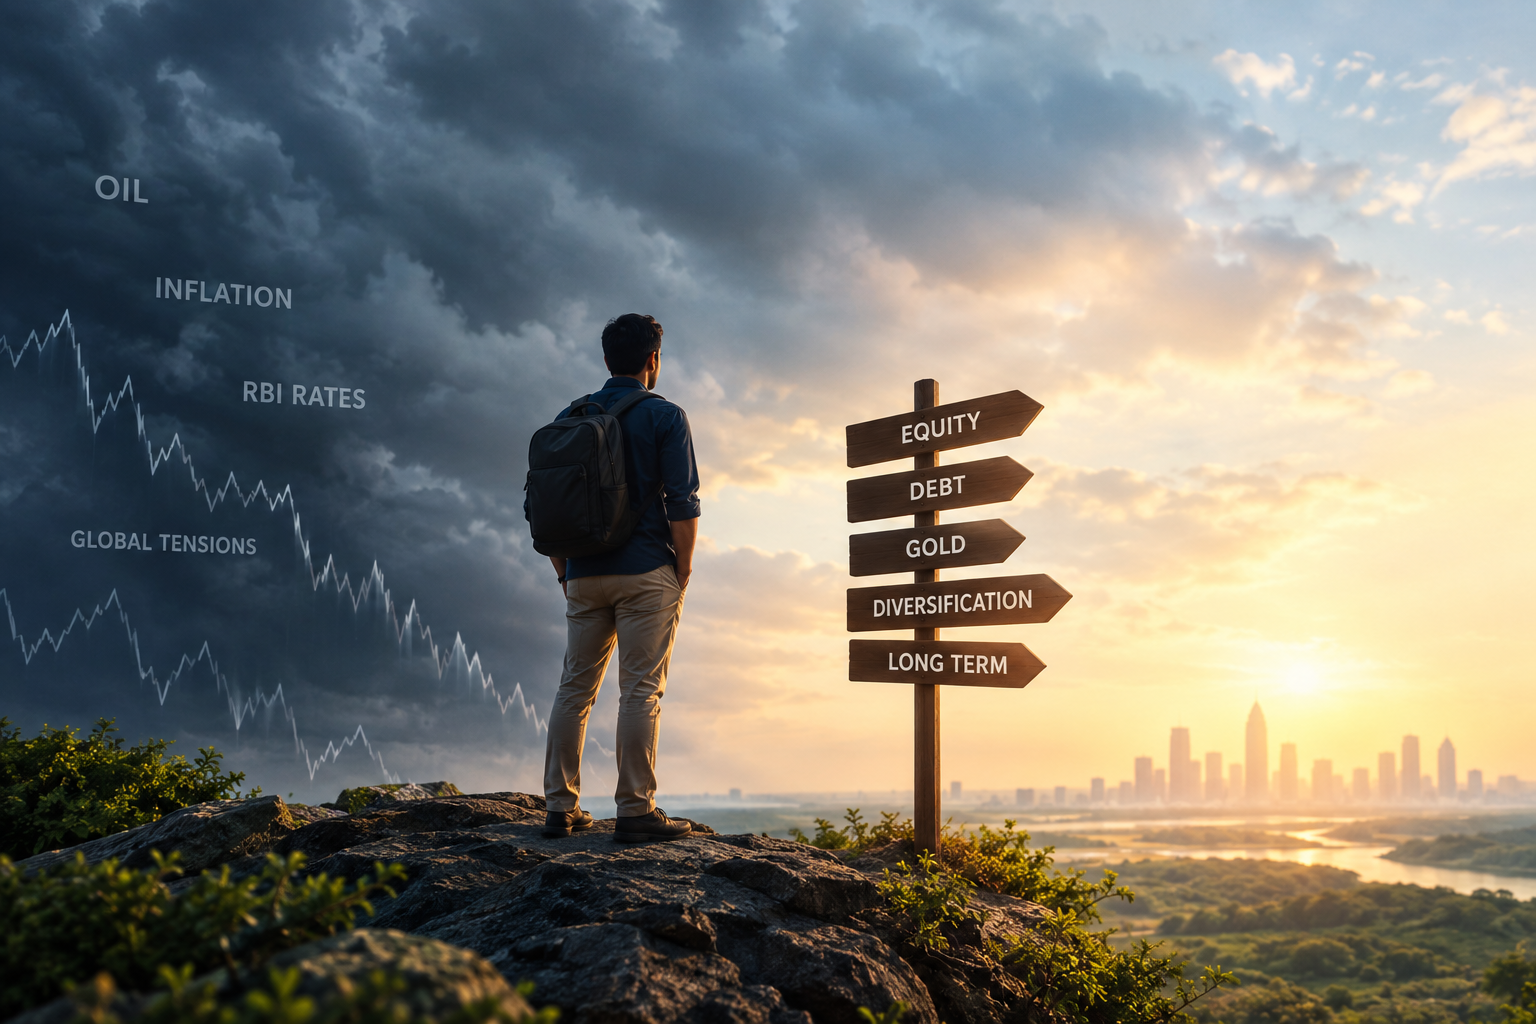
Crude oil has surged above $100 a barrel. Inflation concerns have resurfaced. Bond yields are moving higher. And expectations of RBI rate hikes have returned.
The natural question is: What does this mean for investors?
The New Headwind: Oil
The speed of the shift is what makes this moment striking.
As recently as August, the RBI held rates at 5.25% and maintained a neutral stance, though it raised its FY27 inflation forecast to 5% and its own MPC minutes, released August 20, warned that "a case for a hike may emerge" if Q3 inflation peaks at 5.9%. Then, in the first week of September, Brent crude crossed $100, driven by Houthi strikes on Saudi Arabia's Yanbu terminal and fresh Middle East escalation, and climbed to $109 within days. Oil has since eased to around $103–106 as Saudi Arabia indicated partial pipeline restoration, but remains up over 50% from a year ago.
SBI Research's latest Ecowrap, published this week, is unambiguous. They strongly advocate a 25-basis-point rate hike at the October MPC meeting, followed by another 25 bps in December, taking the repo rate from 5.25% back up to 5.75%. The reasoning: high oil feeds directly into inflation. India imports a significant share of its energy needs. CPI has already been rising for ten consecutive months, July came in at 4.45%, and August was confirmed at 4.82% on September 14, the highest reading since December 2024, with food inflation running at 5.95%. If crude stays elevated, SBI Research estimates October–November CPI could move to 6.5% or higher, well above the RBI's 4% target. The next MPC meeting is October 5–7, the first real test of whether the RBI follows SBI Research's call.
The global picture compounds this. US 10-year yields are approaching 5%. Indian benchmark yields have crossed 7%. Higher rates compress equity valuations and raise borrowing costs for companies. The near-term headwinds are real.
But a headwind is not the same as a change in direction.
Look Beyond the Rate Cycle
Interest rates influence market sentiment. Corporate earnings and economic fundamentals shape the longer-term investment story.
India's GDP is projected to grow at 6.7% this year, the RBI's own August 2026 forecast. Domestic consumption remains robust. Infrastructure investment continues. Corporate earnings have held up well, with mid and small-cap companies posting strong profit growth in recent quarters.
Rate hikes happen in economies that are growing. The RBI does not hike into a recession. The structural growth drivers, demographics, manufacturing, a formalising economy, have not changed because of a spike in oil prices.
Prashant Jain of 3P Investment Managers projected, as recently as July 2026, that Indian equities could deliver 15% annual returns over three years, underpinned by India's balance of payments swinging to surplus. Christopher Wood of Jefferies has continued to call India the strongest long-term structural story in global equities, though he had noted that his near-term positive forecast assumed no major geopolitical shocks to energy prices, a caveat now being tested in real time.
The point is not that these forecasts will play out exactly as modelled. A market forecast is not a financial plan. Investors don't need to correctly predict every movement in oil, interest rates or the Nifty to build long-term wealth. What matters more is having an investment strategy that can withstand periods of uncertainty.
Don't Predict the Storm. Build for It.
This is where asset allocation becomes the real answer.
A portfolio combining equity, debt, gold and liquidity can respond to different market environments without requiring the investor to accurately call every turn. When rates rise and fixed income becomes more attractive, the debt component benefits. When equities correct and valuations improve, the equity allocation is positioned for recovery. Rebalancing, trimming what has held up, adding to what has fallen, mechanically enforces the discipline of buying low without requiring a market call.
Risk management and market timing are not the same thing. One is a structure you build in advance. The other is a prediction you are unlikely to get right consistently.
The precise allocation depends on an investor's goals, time horizon and risk tolerance. The objective isn't to find an allocation that wins in every market. It is to create one that allows you to stay invested through different markets.
The Hardest Part May Be Waiting
After a long period of subdued returns, investors can become impatient. Pause the SIP. Move to fixed deposits. Wait for the correction. Re-enter when the picture becomes clearer.
But markets rarely provide clarity before the opportunity appears. The investors who look back on this period as a great entry point will be the ones who stayed the course through it, not the ones who waited for the headlines to turn positive.
SIPs can continue through volatile periods. Larger investments can be deployed in a manner consistent with your risk profile and time horizon. The equity allocation remains for the recovery that follows every period like this one.
The market may remain uncertain.
Your financial plan doesn't have to be.
---------------------
The views expressed above are for general informational purposes and represent the views and analysis of Fin & Me Wealth Partners LLP (ARN: 194729). They should not be construed as investment advice. Please consult your financial advisor before making investment decisions. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully.
Market data and analyst views referenced: SBI Research Ecowrap (September 2026); Christopher Wood, Jefferies GREED & Fear; Prashant Jain, 3P Investment Managers (July 2026).